Weather insurance confuses a lot of first-time buyers because it doesn’t work like typical event insurance. There’s no need to prove damage, no adjuster walking your venue after the fact, and — most importantly — no requirement that your event actually be cancelled. Here’s exactly how it works.
It’s Based on a Trigger, Not a Judgment Call
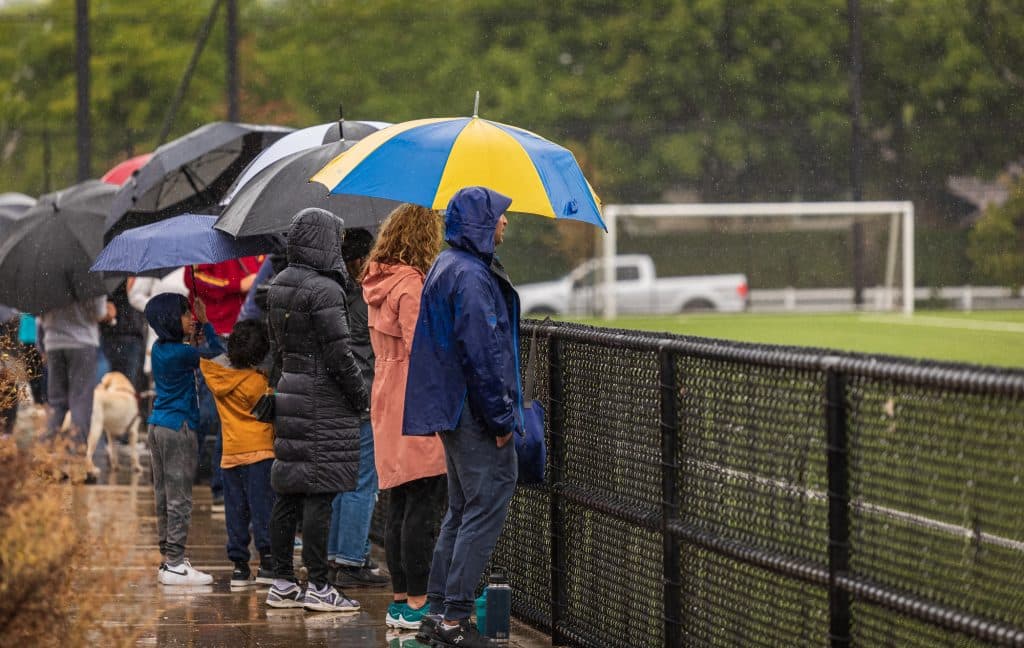
Most weather insurance for outdoor events is a parametric product. That means your policy is built around a specific, measurable trigger — like 0.5 inches of rain during a defined window, or a heat index above 100°F during specified hours. If that trigger is met according to verified data, your policy pays out automatically. There’s no debate about whether the event “felt” impacted enough.
This is what makes rain insurance and other weather products fundamentally different from general liability coverage — and it’s also what makes them faster and more predictable at claim time.
Step 1: Define Your Coverage Window
Before anything else, you and your broker define the specific hours or days your policy protects. This might be:
-
A single afternoon for a one-day fair
-
Setup day and event day covered separately (dual-period coverage)
-
An entire multi-day festival or tournament schedule
Step 2: Choose Your Trigger and Threshold
Next, you set the condition that triggers a payout. Common options include:
-
Rainfall accumulation — a set amount of rain during your coverage window
-
Adverse weather — lightning, high winds, severe thunderstorms, or tornadoes serious enough that a local authority would deem the event unsafe, addressed through adverse weather insurance
-
Heat index — a temperature-and-humidity threshold addressed by heat index insurance
-
Stepped thresholds — up to three trigger levels, each tied to a larger payout as severity increases
Step 3: Set Your Insured Amount
Your insured amount should reflect your actual financial exposure — lost ticket revenue, non-refundable deposits, vendor guarantees, or production costs. This is where working with a specialist matters: an accurate insured amount means you’re neither underinsured nor overpaying for coverage you don’t need.
Step 4: The Event Happens — Weather Is Measured
During your coverage window, weather conditions are tracked using verified data sources, most commonly the National Weather Service and NOAA. There’s no need for the event to be cancelled, delayed, or visibly disrupted for a claim to be valid — only for the pre-agreed trigger to be met.
Step 5: File and Receive Your Claim
If your trigger is met, filing a claim typically involves:
-
Contacting your claims team with your policy details
-
Providing verified weather data for your coverage window and location
-
Submitting any required documentation
-
Receiving a payout based on your policy terms — often without an audit or lengthy adjustment process
For risks that fall outside weather entirely — like a power outage or vendor cancellation — event cancellation insurance works alongside weather coverage to close the remaining gaps.
Why the Details Matter — and Why Spectrum Gets Them Right
Setting the right trigger, threshold, and coverage window requires real meteorological insight, not guesswork. Spectrum Weather Insurance’s on-staff meteorologist helps structure policies around historical weather data for your specific date and location, while our access to multiple highly rated carriers ensures you’re comparing real options, not accepting the first quote.
Ready to Set Up Your Policy?
Understanding how weather insurance works is the first step — the next is building a policy around your actual event. Contact Spectrum Weather Insurance or call 816-810-2346 to get started.